Digital euro: 2027, the year of execution — what the trilogue, Rulebook v0.91 and the ECB pilot change for Belgian banks
The European CBDC has moved beyond PowerPoint presentations. Parliament has adopted its negotiating mandate, the ECB has published Rulebook version 0.91 and selected 36 providers for a large-scale pilot. For Belgian institutions, the question is no longer “if”, but “how”.
Executive Summary
The digital euro is no longer a theoretical project: on 9 July 2026, the European Parliament adopted its negotiating mandate in plenary (416 votes in favour, 169 against, 22 abstentions), and the trilogue with the Council has begun. At the same time, in July 2026 the ECB published Rulebook version 0.91 and selected 36 payment service providers (PSPs) from more than 50 applicants for a pilot scheduled to start in the second half of 2027 — with the National Bank of Belgium among the 19 participating central banks. For Belgian banks, the time for monitoring is over: they now need to decide how to integrate a public form of money that could fundamentally reshape the retail payments landscape, from the compensation model to coexistence with Bancontact. Actual issuance remains conditional on adoption of the regulation, with a potential launch window in 2029 — meaning roughly two and a half years to prepare, and not a day more.
Context & Background
A decade of maturation, a decisive summer
The digital euro project dates back to the ECB's work initiated around the beginning of the 2020s. Official milestones followed one another: the launch of the preparation phase by the Governing Council on 18 October 2023, followed by the move to the next phase on 1 November 2025, with the stated objective of preparing for “a possible first issuance during 2029”.
Summer 2026 accelerated everything. Three events in three weeks:
23 June 2026 — The European Parliament's ECON Committee approved the digital euro legal framework and mandated the immediate opening of trilogue negotiations with the Council.
9 July 2026 — The plenary confirmed the mandate by 416 votes to 169, with 22 abstentions, following an attempt by right-wing groups to derail the vote.
14 July 2026 — The ECB selected 36 PSPs for the pilot, from more than 50 applications received following its 5 March 2026 call for expressions of interest.
Why now? The geopolitics of payments
It is no coincidence that the file moved forward in 2026. The stated rationale is monetary sovereignty: according to ECB data, Visa and Mastercard account for 61% of card payments in the euro area and process almost all cross-border card transactions. While China has already launched its digital yuan and Russia is due to make its digital rouble operational in September 2026, Washington has taken the opposite route: the Trump administration abandoned the idea of a Federal Reserve digital dollar and is betting on private stablecoins.
The result: Europe finds itself alone in defending public digital money as a counterweight to card duopolies and dollar-denominated stablecoins. National central banks — including the NBB — are clearly reinforcing this position.
In-Depth Analysis
1. The trilogue: three decisions that will hurt
The mandate adopted in plenary is not a formality. Three issues are at the centre of the tensions, and they directly affect banks' economics.
First, distributor compensation. The proposed model would have banks and PSPs distribute the digital euro — they would manage the customer relationship, app integration and KYC — but compensation for this role remains the most contentious point in negotiations with Member States, according to three sources close to the discussions cited by Euronews. If Parliament pushes for a free basic service for citizens, banks are reminding policymakers that they are not utilities. The risk of an asymmetric business model — infrastructure costs to be borne while distribution revenues are capped — is real.
Second, the holding limit. The individual holding limit for digital euros has not yet been determined. This is the unknown that will determine the scale of the liquidity shift from deposits into central bank money: too low, and it constrains adoption; too high, and it could weaken bank funding. Do not rely on any figure currently circulating: no amount had been published by the co-legislators at the time of writing, and nothing has been finalised.
Third, the status of cash. The “single currency” package adopted by ECON guarantees the legal tender status of banknotes — a condition set by several Member States, including Germany, for accepting the CBDC. The final balance between “the digital euro complements cash” and “the digital euro cannibalises cash” will be determined by the details of the regulation.
2. Rulebook v0.91: when the ECB writes the operating manual
Published in July 2026, Rulebook version 0.91 is the document that every institution will have to implement in order to participate in the scheme. It incorporates feedback from the large-scale market consultation conducted by the ECB and the Rulebook Development Group between June and October 2025, bringing together banking, merchant and consumer associations.
What this means in practical terms is that technical standards, certification procedures, settlement specifications and branding rules are being finalised even before the regulation is adopted. This is a deliberate choice by the ECB: prepare the ecosystem so as not to lose time once the legislation is adopted. But it is also a signal: institutions that wait until the end of the trilogue to take an interest in the project will arrive two years behind those already testing the specifications.
3. The 2027 pilot: 36 PSPs, 19 central banks, 4 use cases
The pilot is the first full-scale test of the scheme. Selected from more than 50 applications, the 36 PSPs cover “a wide range of business models, sizes and geographies”.
The setup:
A “beta digital euro” — functionally close to the digital euro envisaged by the draft regulation, but without legal tender status. An important clarification: this is not the digital euro itself, but its full-scale prototype.
A scope: the ECB and 19 national central banks, including Belgium — end users will be Eurosystem staff and selected merchants.
A timetable: operational phase in the second half of 2027, lasting 12 months, with a possible six-month extension at the discretion of the contracting national central bank.
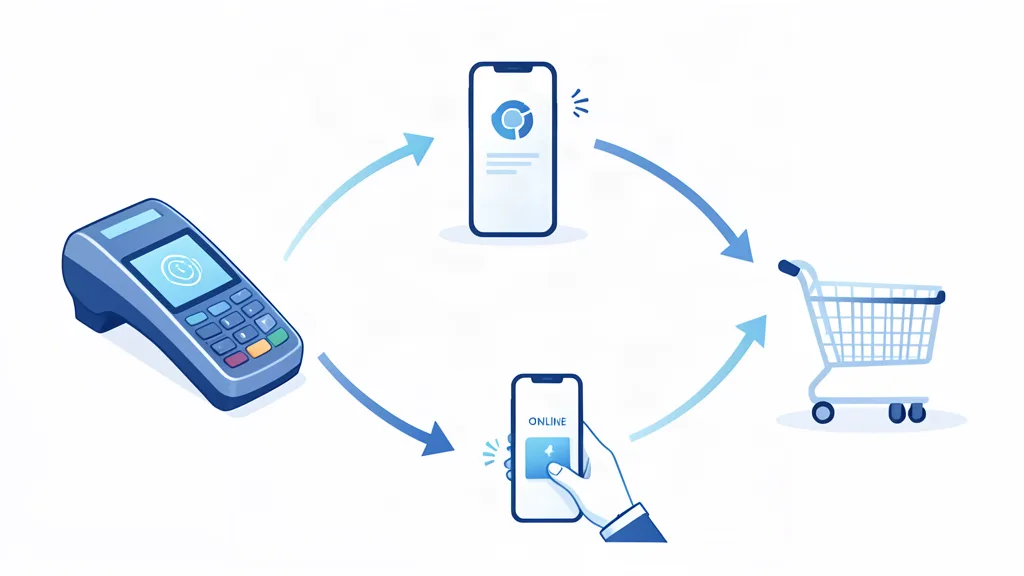
Two roles: “distributor” PSPs provide pilot services to end users (Eurosystem staff); “acquirer” PSPs manage merchant acceptance (SoftPOS, e-commerce). Some PSPs will perform both roles.
Four use cases: online person-to-person payments, NFC-based offline P2P payments (the “digital cash” proposition), in-store payments through SoftPOS, and e-commerce — including mobile e-commerce.
The ambition is clear: test the system under real-world conditions — ECB cafeteria, cafés in Frankfurt, volunteer e-commerce merchants — before making any decision on issuance. It is worth repeating: no issuance decision has been taken, and it will only be made after the regulation is adopted.
4. Belgium: an ideal — and distinctive — testing ground
Belgium's payments landscape has a feature shared by few European countries: a dominant domestic debit scheme, Bancontact/Payconiq, backed by 2.3 billion payments in 2022, up 54.5% over five years.
This is both an advantage and a challenge. An advantage because a market accustomed to an efficient domestic rail is culturally ready for a pan-European standard. A challenge because the digital euro raises existential questions for Bancontact: how does a public wallet that is “free for basic use” and accepted throughout the euro area coexist with a private scheme whose value is based on local dominance? The answers have not yet been written, and Belgian banks that are shareholders in Bancontact will have to negotiate them — rather than simply absorb the consequences.
Institutionally, the NBB has been involved from the outset. As a member of the Eurosystem, it has integrated the digital euro into its preparatory work and consults market participants through the National Retail Payments Committee. Belgium is also one of the 19 countries whose central bank will host the pilot.
What has been decided and what has not yet been decided
Decided at this stage: the principle of a European central bank digital currency; the distribution model through banks and PSPs; the pilot with a beta version without legal tender status; and the continued legal tender status of banknotes (the “single currency” package).
Under negotiation or not yet decided: distributor compensation, the most contentious point in the trilogue; the holding limit — no amount had been published by the co-legislators at the time of writing; the final balance between complementarity and competition with cash; and the issuance decision itself, which will belong to the Eurosystem and can only take place after the regulation is adopted — with no automaticity.
Concrete Cases & Examples
Worldline: the infrastructure preparing for launch
The first tangible example of the emerging value chain is Worldline, a European payments leader whose Belgian activities originate from the former Banksys network. On 15 July 2026, the company announced that it had been selected by the ECB. The group will participate in the pilot both as an acquiring PSP and as a technical provider, supporting banks and financial institutions “from infrastructure connectivity through transaction processing to banking-channel integration and merchant acceptance”.
The lesson for Belgian banks is immediate: acquirers and technical providers are not preparing at the last minute — they are already in the pilot. The acceptance infrastructure (SoftPOS, e-commerce) is being built now, with or without them.
The NBB / Belgian market duo
The second example is on the public side: the NBB is playing a dual role. As the national central bank, it will host the pilot and work with the selected Belgian PSPs. As supervisor — the NBB, rather than the FSMA, is the competent authority on this matter — it will have to ensure that credit institutions integrate the digital euro without creating new operational risks. Non-banks remain under the FSMA's remit through their conventional payment activities — the division of responsibilities between the two authorities will not change with the arrival of the CBDC.
What about elsewhere in Europe?
The comparison highlights Belgium's particular situation. In France, the payments ecosystem is structured around the CB card scheme and international networks, with a culture of instant payments driven by the European initiative. In the Netherlands, iDEAL — like Bancontact, a domestic debit scheme — has opted for openness: iDEAL will be the first scheme integrated into the European Payments Initiative (EPI), which underpins the future Wero. The parallel with Bancontact is direct: the path to survival for a domestic scheme in the digital euro era runs through pan-European interoperability, not retreat.
Practical Implications
For executive management and strategy
Put the issue on the board agenda now. The trilogue is targeted for completion by the end of 2026; the pilot starts in 2027. A Belgian bank without a digital euro workstream open by mid-2026 is already a year behind Worldline and the pilot PSPs.
Decide on the distribution model. Becoming a distributor of the digital euro is not really optional — it will be the default channel for distributing central bank money. The questions are: at what cost, with what remuneration, and how will it interact with the deposit offering?
For compliance and risk functions
Map the requirements of Rulebook v0.91: certification, testing and settlement specifications. The Rulebook is becoming the contractual reference for the future scheme — read it now, not in 2028.
Anticipate new risks: money laundering through offline payments, management of holding limits once the figure is known, and business continuity on central bank money infrastructure. AML/CFT frameworks will have to adapt to an instrument that combines some of the anonymity of cash (for small offline amounts) with digital traceability.
For operations and payments functions
Prepare the technical integration: the pilot tests SoftPOS, offline NFC and e-commerce using aliases. Payments teams should build expertise in these use cases, using the specifications published by the ECB.
Negotiate coexistence with Bancontact/Payconiq: positioning of the two rails, pricing and user experience. This is a commercial and technical workstream, not simply a compliance exercise.
For treasurers and asset-liability management
Model the impact of the holding limit on retail deposits. Several scenarios — low/high limit and different adoption rates — should be prepared as soon as the trilogue reaches a decision.
Key Takeaways
The trilogue is expected to conclude before the end of 2026: Parliament adopted its mandate on 9 July 2026 (416 in favour, 169 against, 22 abstentions). The priority issue to monitor is distributor compensation, as this will determine each bank's economic model within the scheme.
Rulebook v0.91 (July 2026) is locking in the standards — certification, settlement and branding — even before the regulation is adopted.
The pilot starts in the second half of 2027: 36 PSPs selected from more than 50 applicants, with two roles (distribution and acquiring), 12 months (+6 possible), and Belgium among the 19 participating countries.
The holding limit and distributor compensation remain undecided: the co-legislators had published no amount at the time of writing. Prepare scenarios (low/high limit and adoption rates) rather than a single assumption.
For Belgium, the challenge is twofold: prepare for integration (NBB in the pilot, Worldline as acquiring/technical PSP) and negotiate coexistence with Bancontact/Payconiq (2.3 billion payments in 2022).
Roadmap / Upcoming Deadlines
Deadline | Event | Source |
|---|---|---|
Q3–Q4 2026 | Parliament/Council trilogue; finalisation of the regulation targeted before the end of 2026 | Euronews |
Q3 2026 – H1 2027 | Pilot development: participation agreements, PSP integration, back-end certification | ECB Pilot FAQ |
H2 2027 – H2 2028 | Operational pilot phase (12 months, with a possible six-month extension) | ECB Pilot FAQ |
2028 | Eurosystem issuance decision — possible only after the co-legislators adopt the regulation; discretionary decision, with no automaticity | NBB / ECB Pilot FAQ |
2029 | Potential first issuance of the digital euro | ECB Pilot FAQ |